Backtesting by hand: how many trades do you collect before trusting a setup?
Manual backtesting — scrolling back, marking setups, recording results — is slow but teaches more than any automated run. The question is always sample size: twenty trades is noise, two hundred is information.
What's your standard?
- how you run a manual backtest
- the trade count you require before going live
- how you keep the test honest (no hindsight editing)
The expectancy guide tells you how to read the results.
Background: Risk-reward ratio, win rate and expectancy: the maths behind a trading edge
A high win rate can still lose money. See how win rate and risk-reward combine into expectancy, with break-even win rates and worked examples.
What is a good risk-reward ratio in forex?
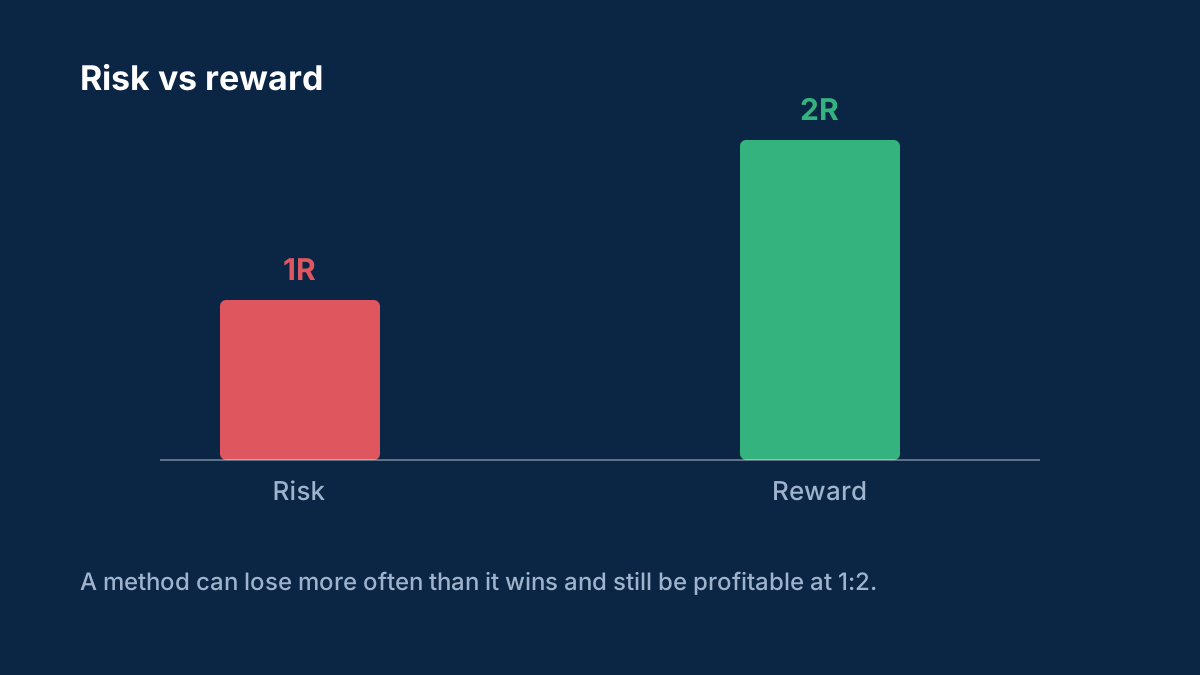
There isn't one right ratio. What matters is expectancy, the win rate and ratio together. A 1:2 ratio breaks even at about 33% winners before costs, while a 1:1 ratio needs 50%.
How do you calculate trading expectancy?
Multiply the win rate by the average win and subtract the loss rate multiplied by the average loss. Measuring wins and losses in multiples of the amount risked (R) makes the result easy to compare.
Comments
Log in to join the discussion. Comments follow the community guidelines.
Log in to commentLoading comments…