Triangular arbitrage: does it exist for retail traders?
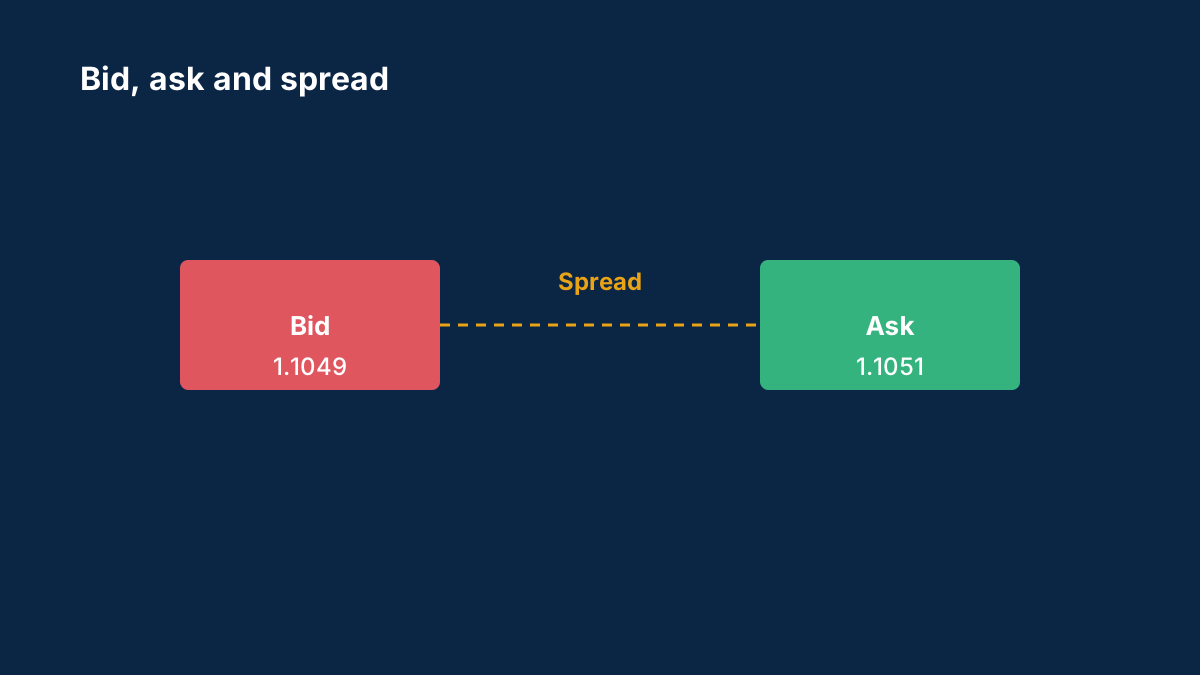
Triangular arbitrage exploits mispricing across three pairs — the classic EUR/USD × GBP/USD × EUR/GBP triangle. In theory it's riskless; in practice the discrepancies are microseconds wide and the costs eat them.
Have you tried?
- what you found when you looked for mispricing
- how spreads and latency ended the dream
- the educational value of the attempt
The cross rates guide explains the triangle maths.
Background: Cross rates explained: how EUR/GBP and EUR/JPY are calculated from dollar pairs
A cross rate is an exchange rate between two currencies that doesn't include the US dollar. How cross rates are derived from dollar pairs, with worked examples, and why crosses often cost more to trade.
What is a cross rate in forex?
An exchange rate between two currencies that doesn't include the US dollar, such as EUR/GBP, EUR/JPY or AUD/NZD.
How do you calculate EUR/GBP from EUR/USD and GBP/USD?
Divide EUR/USD by GBP/USD. With EUR/USD at 1.1050 and GBP/USD at 1.3000, EUR/GBP is 0.8500.
Comments
Log in to join the discussion. Comments follow the community guidelines.
Log in to commentLoading comments…