Overfitting: how do you know you've done it?
An overfitted strategy is tailored to the past: perfect on historical data, useless going forward. The tell-tale signs are too many rules, too many parameters and a backtest that's suspiciously smooth.
What's your overfitting checklist?
- the signs you look for in a backtest
- how you simplify a strategy that's too tuned
- the overfitted system you believed in once
The expectancy guide explains the difference between edge and coincidence.
Background: Risk-reward ratio, win rate and expectancy: the maths behind a trading edge
A high win rate can still lose money. See how win rate and risk-reward combine into expectancy, with break-even win rates and worked examples.
What is a good risk-reward ratio in forex?
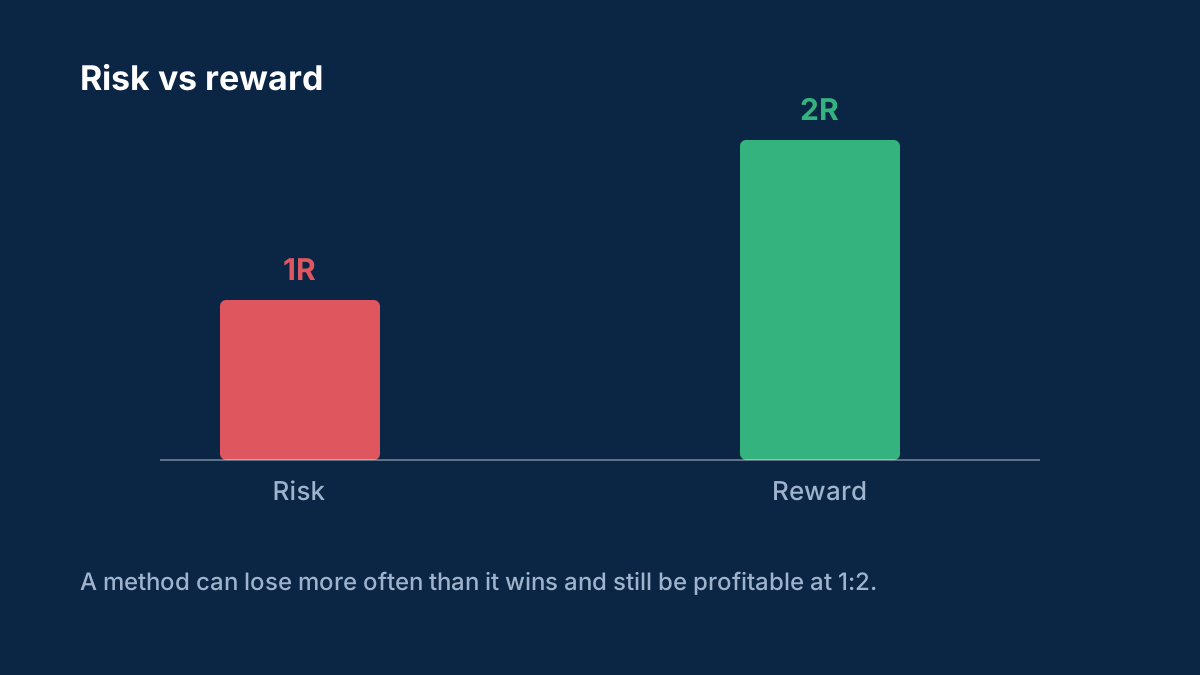
There isn't one right ratio. What matters is expectancy, the win rate and ratio together. A 1:2 ratio breaks even at about 33% winners before costs, while a 1:1 ratio needs 50%.
How do you calculate trading expectancy?
Multiply the win rate by the average win and subtract the loss rate multiplied by the average loss. Measuring wins and losses in multiples of the amount risked (R) makes the result easy to compare.
Comments
Log in to join the discussion. Comments follow the community guidelines.
Log in to commentLoading comments…