Fixed risk-reward versus market-driven exits: which won for you?
Fixed RR exits are mechanical and testable; market-driven exits (structure, supply zones) adapt but resist backtesting. Most traders blend them without knowing which part earns the money.
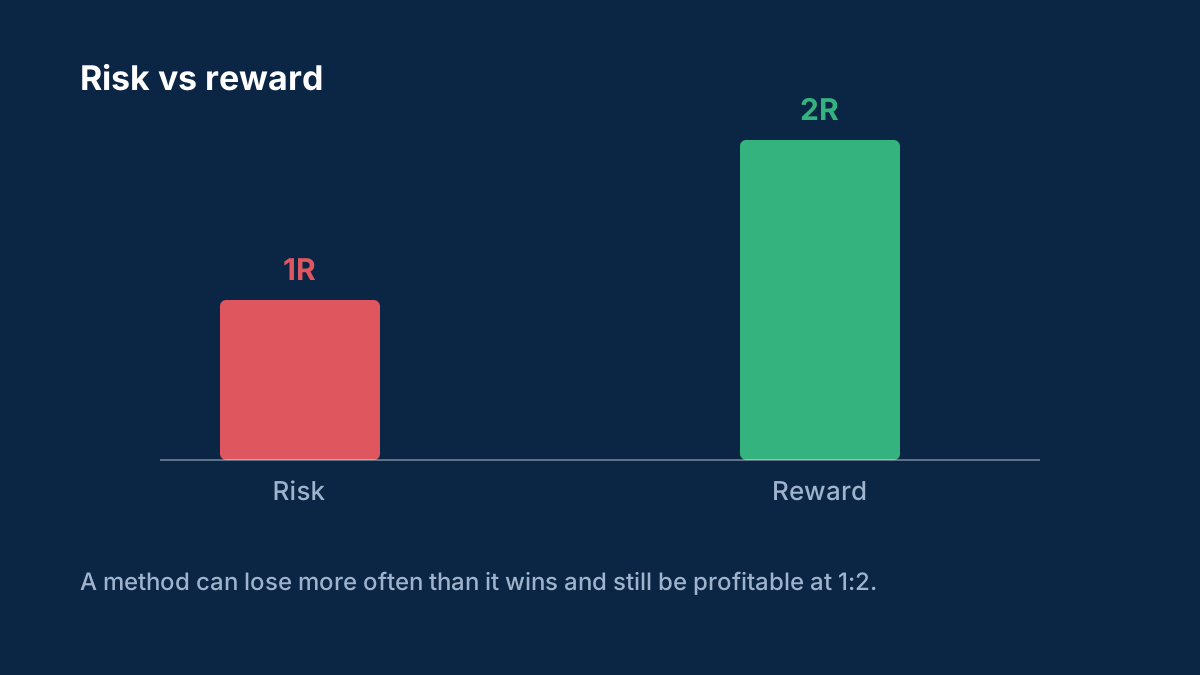
What's your exit architecture?
- the fixed part and the discretionary part
- how you'd know if the discretionary part adds value
- a test that changed your exit rules
The expectancy guide shows how to isolate the answer.
Background: Risk-reward ratio, win rate and expectancy: the maths behind a trading edge
A high win rate can still lose money. See how win rate and risk-reward combine into expectancy, with break-even win rates and worked examples.
What is a good risk-reward ratio in forex?
There isn't one right ratio. What matters is expectancy, the win rate and ratio together. A 1:2 ratio breaks even at about 33% winners before costs, while a 1:1 ratio needs 50%.
How do you calculate trading expectancy?
Multiply the win rate by the average win and subtract the loss rate multiplied by the average loss. Measuring wins and losses in multiples of the amount risked (R) makes the result easy to compare.
Comments
Log in to join the discussion. Comments follow the community guidelines.
Log in to commentLoading comments…