Summer markets: how do you adapt to thin, slow ranges?
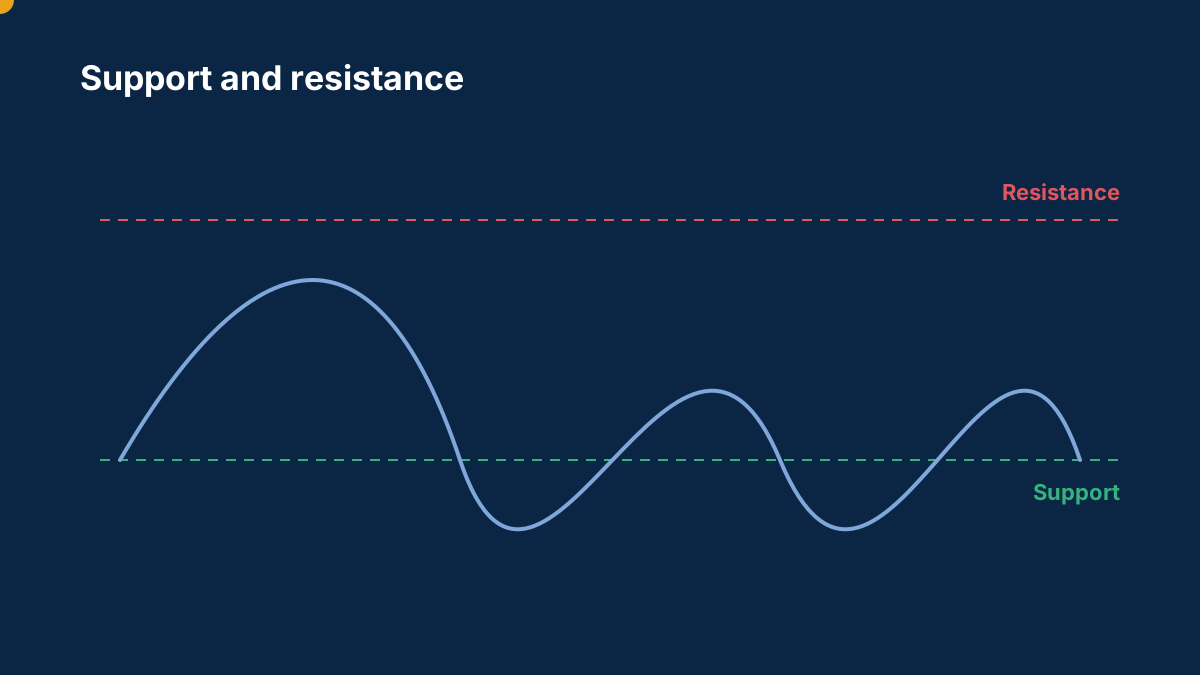
Summer dries the liquidity: narrower ranges, slower moves and more false breaks. Strategies built for autumn volatility can starve in August, and the response is usually to trade less, not harder.
What's your summer mode?
- how your setups change in summer conditions
- the size and frequency adjustments you make
- the summer lesson you now plan for
The ATR guide shows the seasonal volatility shift in the numbers.
Background: Average true range (ATR): measuring volatility and setting stops
ATR shows how far a pair typically moves in a period. Here is how true range is calculated, and how traders use ATR to place stops and size positions.
How is ATR calculated?
True range for each period is the largest of high minus low, high minus the previous close, and low minus the previous close, ignoring signs. ATR averages true range, typically over 14 periods with Wilder's smoothing.
What ATR multiple should I use for a stop-loss?
Many traders use 1.5 to 2 times ATR, but there is no correct number. Wider stops are hit less often and need a smaller position to keep the same amount of money at risk.
Comments
Log in to join the discussion. Comments follow the community guidelines.
Log in to commentLoading comments…